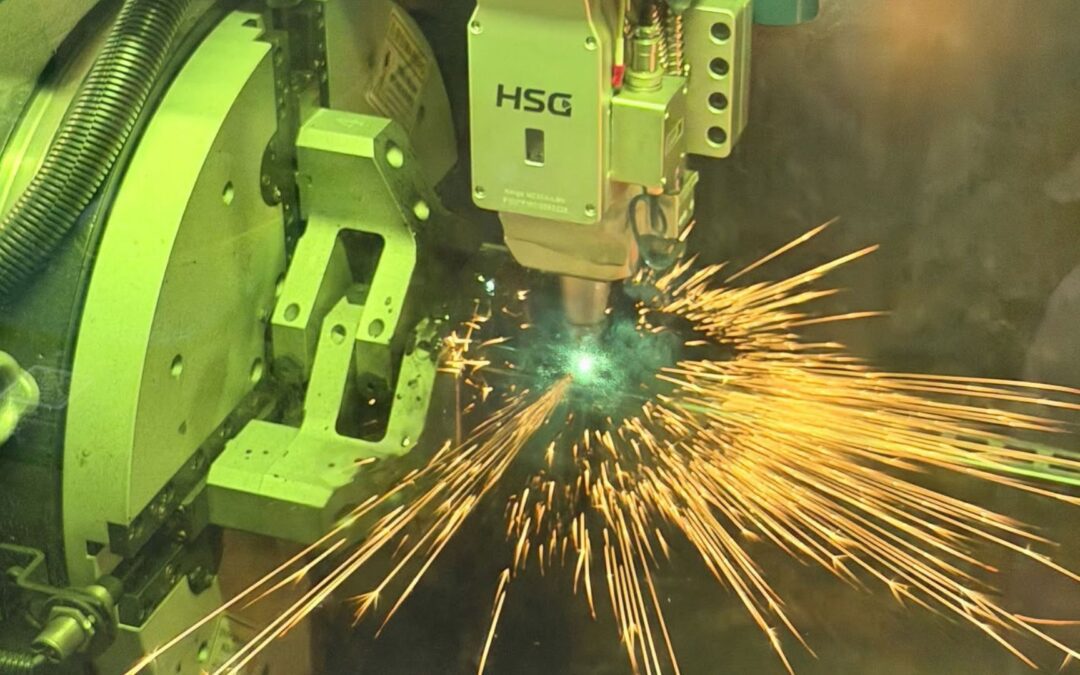
A new fiber laser cutting machine is one of the largest single purchases a Malaysian metal fabrication workshop will make, and paying for it outright can tie up working capital that’s better spent on materials, staffing, or taking on bigger jobs. Machinery financing in Malaysia is well established, and understanding how hire purchase, term loans, and leasing actually differ makes it much easier to structure a deal that fits your cash flow rather than strains it.
Why Financing Usually Beats Paying Cash Upfront
Paying cash preserves a clean balance sheet, but it locks up capital that could otherwise cover raw material stock, payroll, or a second shift of work. Financing spreads the cost of the machine across its productive life, so the repayments can be supported by revenue generated from the machine’s production activities, rather than relying entirely on cash reserves before the machine begins generating income.
The Three Main Ways to Finance a Laser Cutting Machine
- Hire Purchase (HP) — the bank or finance company pays the supplier directly, and you repay in fixed monthly instalments over an agreed tenure. You gradually gain ownership of the machine and typically own it outright once the final instalment has been paid. HP is the most common structure for industrial machinery in Malaysia and usually calls for a down payment.
- Term or Machinery Loan — a business loan secured against company assets, the machine itself, or a director’s guarantee. Funds are disbursed as a lump sum, which makes it easier to bundle in installation, commissioning, and operator training costs alongside the machine price.
- Leasing (Operating Lease) — you pay to use the machine over a fixed period without owning it outright, with the option to renew, upgrade, or return it at the end of the term. This keeps the initial financial commitment low and suits businesses that expect laser source technology to advance rapidly.
Optimizing Your Shop Floor Throughput
The table below summarizes how the three structures generally compare. Actual terms depend on the lender and your business profile.
|
Financing option |
Potential benefit |
Possible consideration |
|---|---|---|
|
Hire purchase |
Potential ownership at the end of the term |
Down payment and fixed repayments |
|
Term loan |
May allow related project costs to be financed |
Interest and security requirements |
|
Leasing |
May offer flexibility for upgrades |
Ownership and end-of-term conditions |
A Simple Example: Comparing Your Options
For example, a workshop purchasing a RM300,000 laser cutting machine may compare the required down payment, monthly repayment, financing period, and total repayment amount under different financing options. This is an illustration only and not a confirmed lender quotation.
What Malaysian Lenders Typically Look At
- At least two years of financial statements or management accounts, along with evidence of steady cash flow.
- A firm, itemised quotation for the specific machine — brand, wattage, work envelope, and included accessories — since most lenders finance a percentage of invoice value rather than the full amount.
- The required down payment may be higher for high-wattage industrial lasers than for some types of general workshop equipment, depending on the lender and financing arrangement.
- Collateral or a director’s personal guarantee, more commonly required from younger or first-time borrowing companies.
Whether the machine is new or used also affects the terms on offer, since financing structures and tenures for used equipment are often tighter than for new machines.
SME and Government-Backed Schemes Worth Asking About
Malaysian banks and agencies such as SME Bank and Bank Negara Malaysia periodically run preferential financing schemes for manufacturing equipment upgrades, sometimes with subsidised rates or extended tenures for SMEs. Eligibility criteria and rates change from year to year, so treat this as a starting point for a conversation with your bank or relationship manager rather than a figure to budget around until it’s confirmed in writing.
Matching the Financing Structure to How You’ll Use the Machine
If your order volume is still growing or you expect to upgrade to a higher-wattage laser within a few years, leasing may provide greater flexibility without tying up capital in an asset you may outgrow. If the laser will be your core production asset for the next five to ten years, hire purchase or a term loan builds equity in a machine you plan to keep and depreciate. Either way, it’s worth budgeting for ongoing consumables and spare parts alongside the financing payment, not just the machine price itself.
Getting Your Machine Specification Ready Before You Apply
Financing applications move faster when the quotation is locked down first. Hasil Karya’s Fiber Laser Cutting Machine range covers a wide span of wattages and bed sizes, and our sales team can prepare a financing-ready quotation with the specification detail most banks ask for. If you’re still comparing cutting technologies, our guide to how laser cutting machines work is a useful starting point before you finalise a spec to finance.
Need help planning your laser cutting machine purchase? Contact Hasil Karya for a machine specification and quotation tailored to your production requirements.
Enquire for machinery in Malaysia!
QUICK LINK
PRODUCTS
LEGALS
CONTACTS
Copyright © 1983-2024 Hasil Karya Sdn Bhd 198301010332 (105695-V) – Your Trusted Industrial Steel Fabrication Machinery Solution Provider. All Rights Reserved.